Inflation Below Comfort Zone
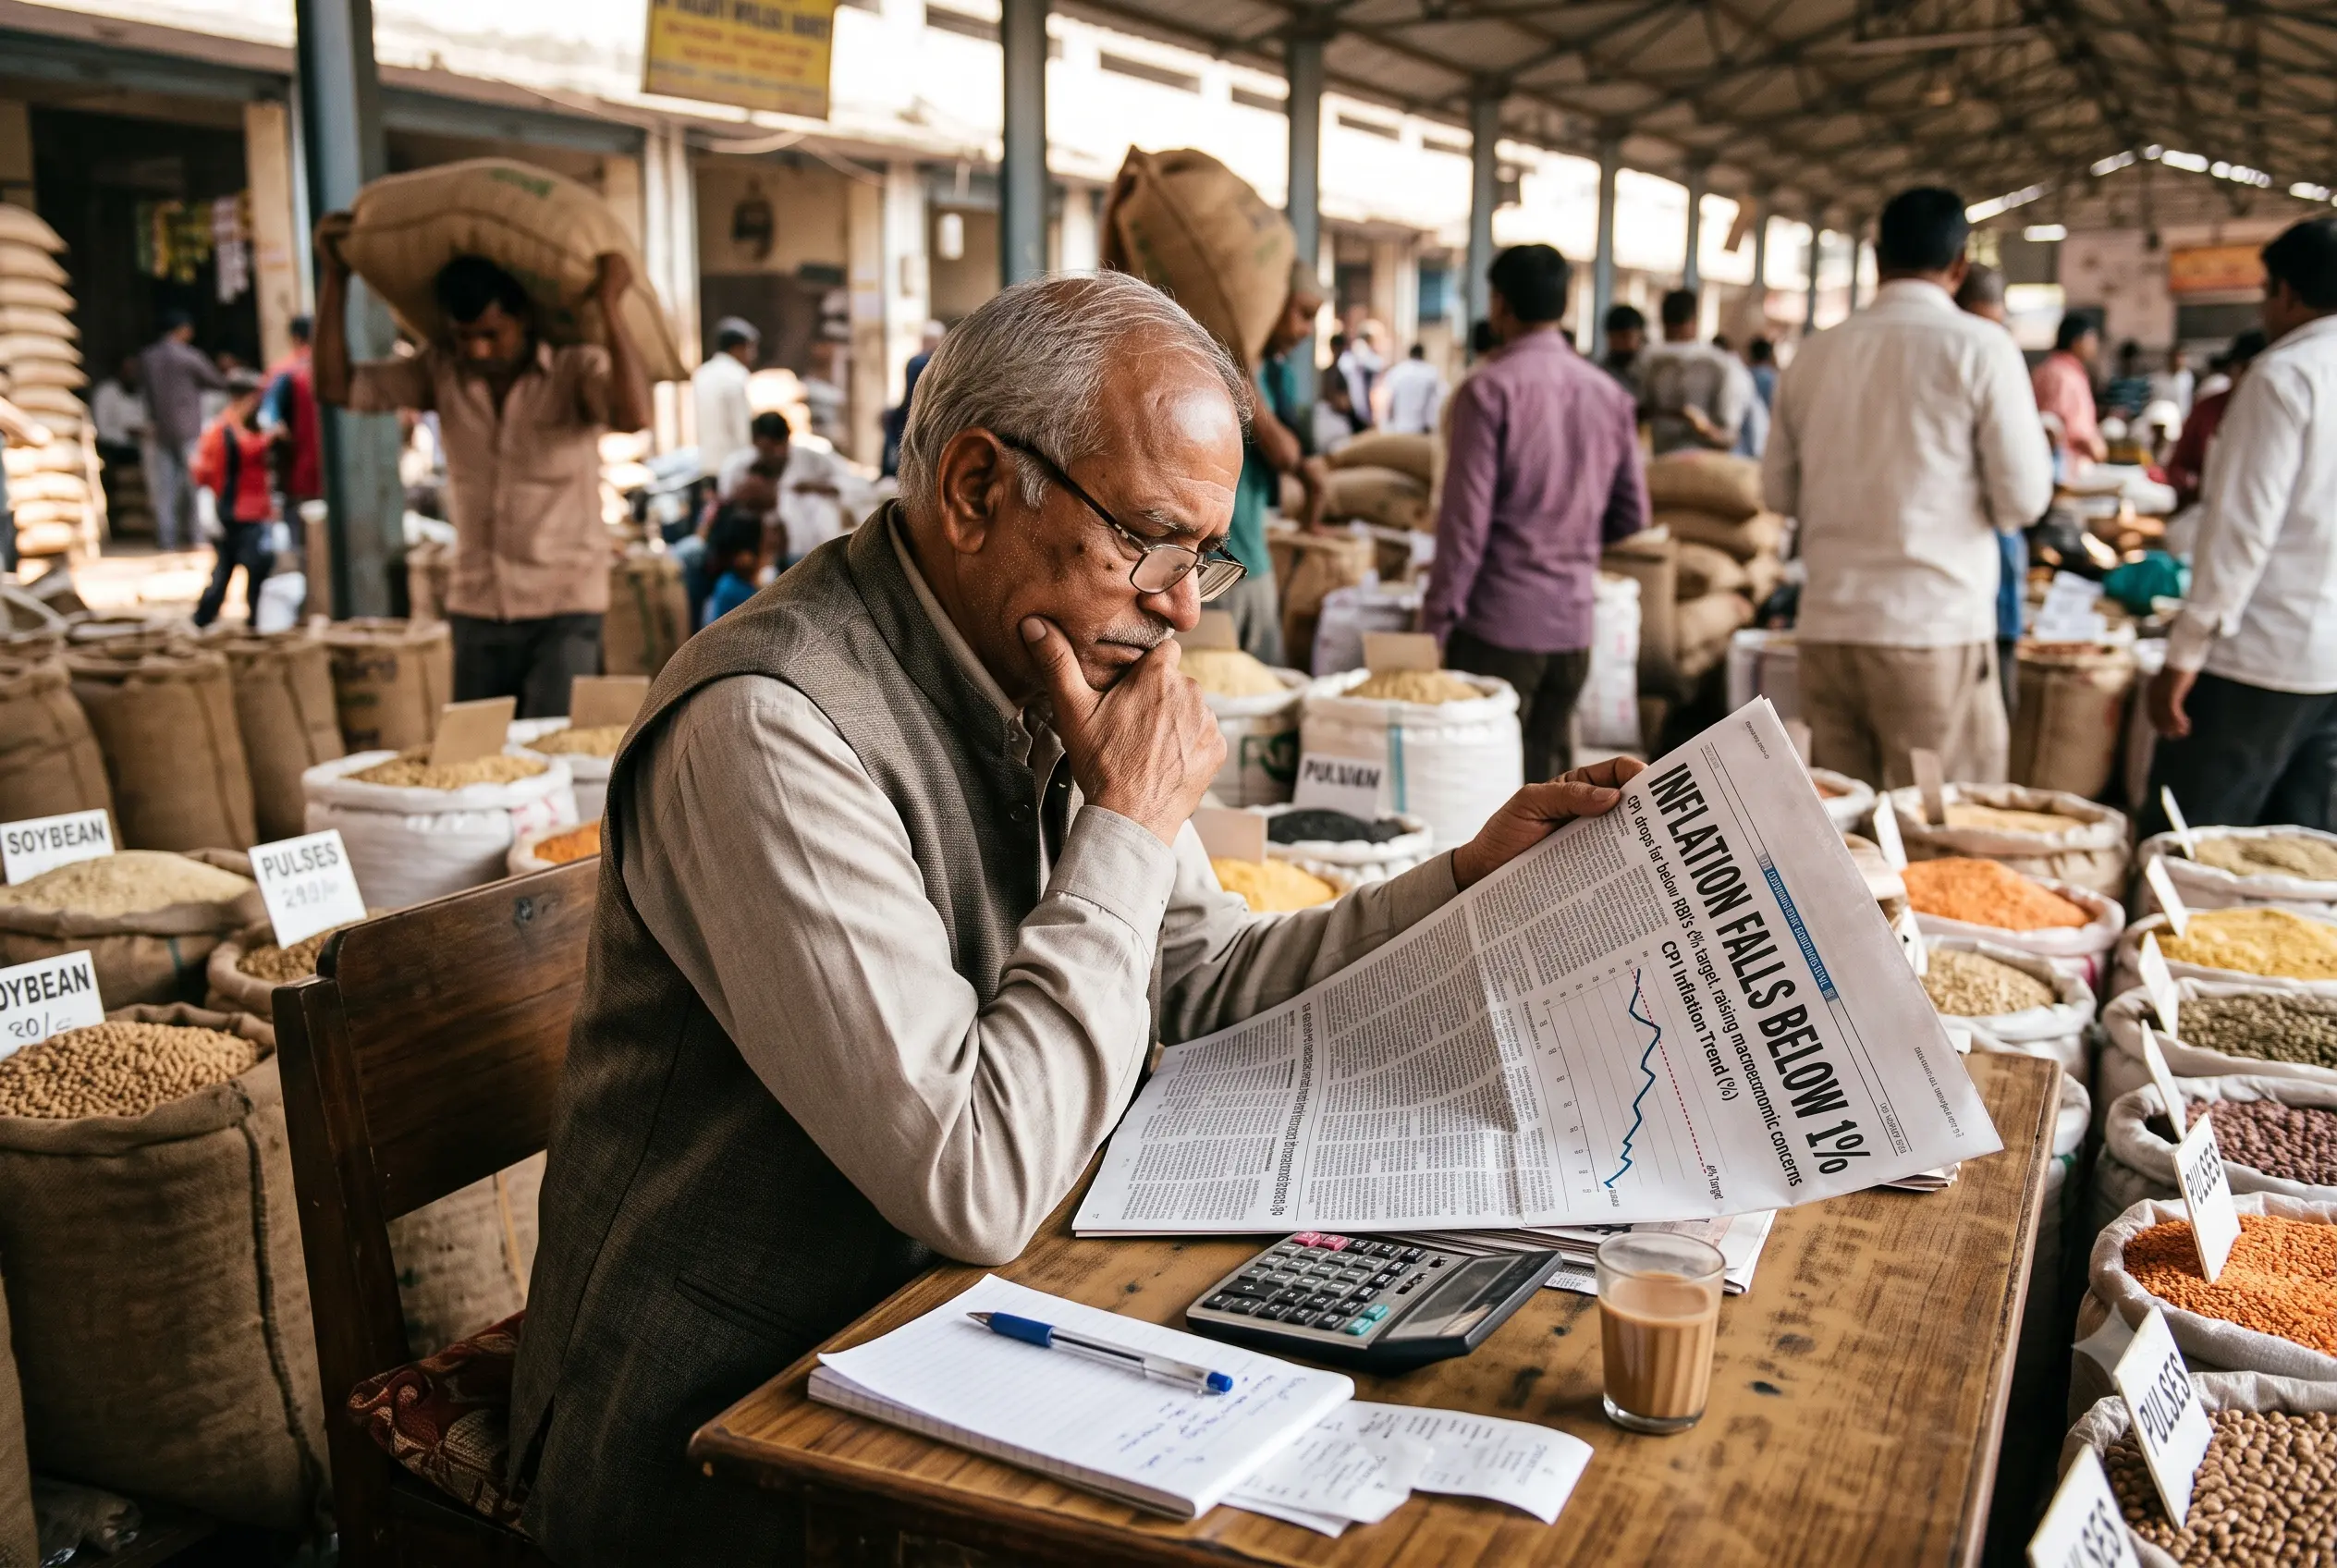
India's CPI inflation has fallen below 1% for two consecutive months, far below the RBI's 4% target. This steep disinflation is raising concerns of macroeconomic stress, impacting rural incomes, corporate margins, and the government's fiscal arithmetic.
Introduction
Context & Background
Key Points
- •Base Effect Distortion: Recent sub-1% CPI prints are partly due to a high statistical base from last year, masking underlying price pressures and limiting policy clarity.
- •Perception Gap: RBI surveys (Nov 2025) show households perceive inflation at 6.6% currently and 7.6% three months ahead, indicating weak credibility of headline numbers.
- •Monetary Policy Dilemma: With inflation low and growth buoyant, rate cuts seem logical; however, a future inflation rebound due to base effects may force policy reversals, unsettling markets.
- •Rural Income Stress: Negative food inflation reduces farm realisations; crops like soybean and pulses sold below MSP in Oct–Nov, compressing rural incomes despite good output.
- •Manufacturing Margin Pressure: Low WPI and muted core CPI for manufactured goods reflect weak pricing power, squeezing corporate margins even if volumes rise.
- •GST Revenue Slowdown: Lower inflation dampens nominal transaction values; GST collections have slowed, partly due to lower price growth and rate rationalisation.
- •Fiscal Arithmetic Risk: Nominal GDP growth is barely above Real GDP, unlike the historical 3–4 percentage point gap, complicating deficit targets and FY27 projections.
Key Concepts in Inflation Targeting
| Concept | Description | Bookmark |
|---|---|---|
| Headline Inflation | Inflation based on all types of commodities in the economy. | |
| Core Inflation | Inflation excluding volatile food and fuel items. | |
| Inflation Target | 4% with a tolerance band of +/- 2% (ranging from 2% to 6%). | |
| CPI-Combined | India's official inflation indicator for monetary policy under the FIT framework. |
Implications of Low Inflation on Key Stakeholders
| Stakeholder | Implication | Bookmark |
|---|---|---|
| Households | Urban consumers may benefit temporarily, but income-linked groups face uncertainty. | |
| Farmers & MSMEs | Price deflation without income buffers leads to demand compression & debt stress. | |
| Government | Lower nominal growth weakens tax buoyancy and fiscal space. | |
| RBI | Managing expectations becomes harder when headline inflation diverges from lived experience. |
Related Entities
Impact & Significance
- •Macro-Fiscal Stress: A nominal GDP growth barely above real GDP reduces tax buoyancy and strains the government's fiscal deficit arithmetic and FY27 projections.
- •Rural Distress: Negative food inflation translates directly to lower farm realizations, compressing rural incomes when crops are sold below the Minimum Support Price (MSP).
- •Corporate Margin Compression: Low WPI and muted core CPI indicate poor pricing power, squeezing margins for MSMEs and large manufacturers despite volume growth.
Challenges & Criticism
- •Credibility Gap: A stark contrast exists between the headline inflation figures (sub-1%) and household perceptions (6.6%), challenging the credibility of official indices.
- •Statistical Distortions: Base effects from the previous year heavily skew current data, masking the true underlying economic pressures and limiting policy clarity.
- •Policy Rigidity: The RBI faces a dilemma where immediate rate cuts seem logical, but the risk of a sudden inflation rebound forces policy hesitation, unsettling financial markets.
Future Outlook
- •Policy Rate Adjustments: The RBI faces a dilemma in balancing potential rate cuts against the risk of a future inflation rebound due to statistical base effects.
- •Rural Income Support: Interventions may be required to support farmers facing distress, particularly ensuring that crop realizations do not fall below the Minimum Support Price (MSP).
- •Fiscal Realignment: The government may need to adjust fiscal deficit targets and budget projections for FY27 to account for compressed nominal GDP growth.
UPSC Relevance
- • GS-3 (Indian Economy): Issues relating to growth, development, and macroeconomic stability; Monetary policy and Flexible Inflation Targeting (FIT).
- • Prelims Focus: CPI vs WPI, Headline vs Core Inflation, RBI's Monetary Policy Committee (MPC) framework.
- • Mains Focus: Analyzing the structural impacts of prolonged disinflation on the rural economy, tax collections, and fiscal deficit.
Sample Questions
Prelims
Consider the following statements regarding Inflation Targeting in India:
1. Core inflation includes the price volatility of food and fuel items.
2. The inflation target under the RBI Act is determined by the Government of India in consultation with the RBI.
3. CPI-Combined is used as the official indicator solely for calculating the Wholesale Price Index (WPI).
Answer: Option 2
Explanation: Statement 1 is incorrect; Core inflation excludes food and fuel items. Statement 2 is correct; the target is set by GoI in consultation with RBI. Statement 3 is incorrect; CPI-Combined is the official inflation indicator for monetary policy, not WPI.
Mains
“Prolonged disinflation can act as a macroeconomic stress rather than a relief.” Discuss the implications of sub-1% CPI inflation on India's fiscal arithmetic, rural incomes, and monetary policy.
Introduction: Define the Flexible Inflation Targeting (FIT) framework in India (4% +/- 2%). Mention the recent context of CPI falling below 1% and the immediate concerns it raises.
Body:
• Macroeconomic Stress: Base effect distortions mask underlying price pressures; weak pricing power squeezes manufacturing margins; perception gap among households regarding actual inflation.
• Fiscal & Rural Impact: Nominal GDP nearing Real GDP complicates deficit targets and slows GST tax buoyancy. Farmers face severe distress as crop prices fall below MSP despite good output.
• Monetary Policy Dilemma: The RBI struggles with rate cuts due to fears of future inflation rebounds, complicating the management of market expectations.
Conclusion: Conclude by highlighting that while high inflation is detrimental, extremely low inflation disrupts income distribution and fiscal planning, necessitating a balanced and flexible approach by the Monetary Policy Committee.