RBI Proposes Fresh Licensing Window for UCBs
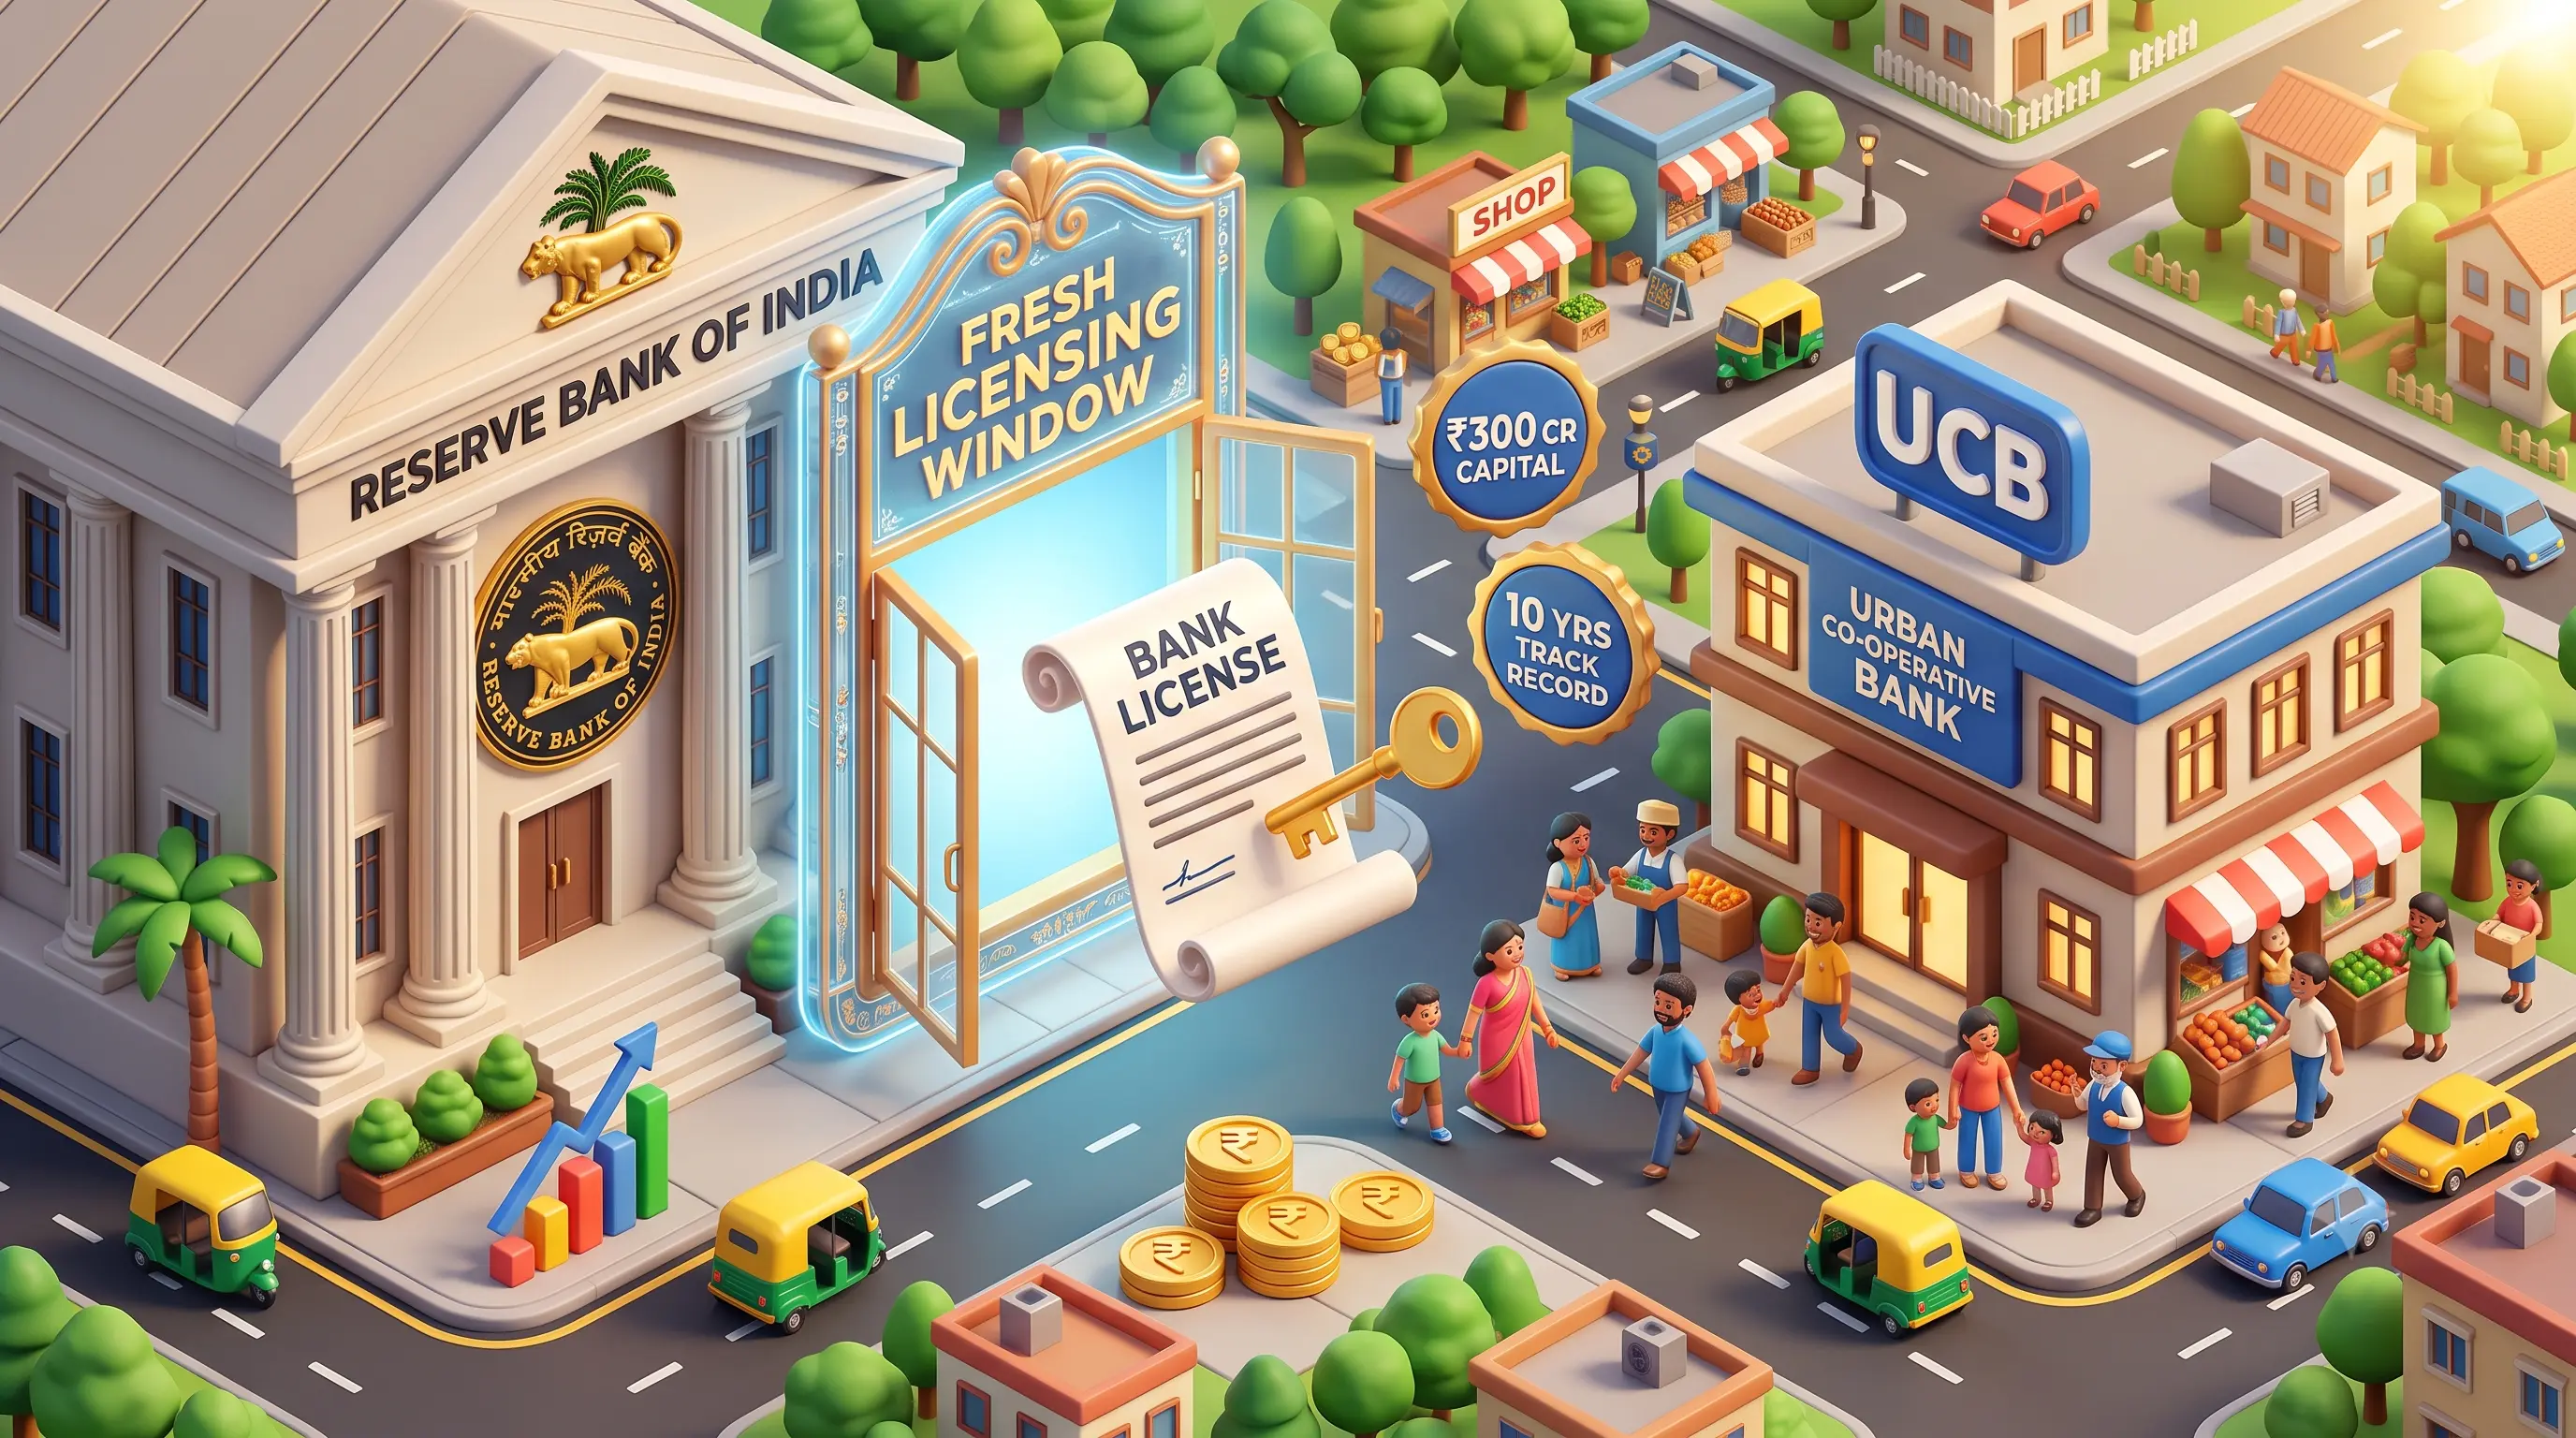
After a 22-year pause, the Reserve Bank of India (RBI) has proposed reopening licences for Urban Co-operative Banks (UCBs). This initiative targets financially strong credit societies to enhance competition and serve urban communities, implementing strict eligibility filters based on the R Gandhi Committee's recommendations.
Introduction
Context & Background
Key Points
- •Restarting Licensing: The RBI plans to reopen the UCB licensing window with stricter entry norms, addressing the historical failures of newly licensed small UCBs.
- •Dual Regulatory Framework: UCBs are regulated by the RBI (for banking functions, capital adequacy, risk norms) and the Registrar of Cooperative Societies (RCS) (for registration, internal governance, audits, and liquidation).
- •Preference for Large Societies: Licences will mainly be granted to large co-operative credit societies that demonstrate a longer track record, stronger governance, and financial maturity.
- •Multi-State Priority: Multi-state co-operative credit societies will be preferred as applicants. Select uni-state societies may be considered if they meet wider footprint conditions.
- •Wider Footprint: The RBI emphasizes that new UCBs must have a broad presence to effectively compete with Small Finance Banks (SFBs), commercial banks, and Non-Banking Financial Companies (NBFCs).
Eligibility Filters for New UCB Licensing
| Parameter | Eligibility Requirement | Bookmark |
|---|---|---|
| Minimum Capital | ₹300 crore capital as on March 31 of the previous FY. | |
| Track Record | 10 years of active operations and a 5-year good financial track record. | |
| Performance Trend | Positive, progressive financial & operational trends over the last 5 years. | |
| Capital Strength (CAR) | Capital Adequacy Ratio must be at least 12% at the time of licence grant. | |
| Asset Quality | Net Non-Performing Assets (NNPA) must not exceed 3% at the time of licence grant. |
Current Status of UCBs in India (2025)
| Indicator | Current Statistic | Bookmark |
|---|---|---|
| Total Bank Count | 1,457 UCBs (838 Tier 1, 535 Tier 2, 78 Tier 3, 6 Tier 4) | |
| Deposit Concentration | 7% of UCBs (deposits above ₹1,000 cr) hold 62.5% of sector deposits | |
| Balance Sheet (2025) | Assets: ₹7.38 lakh crore | Deposits: ₹5.84 lakh crore | |
| Capital Adequacy | Average CAR 18.0%; ~92% UCBs have CAR above 12% | |
| Asset Quality (FY25) | GNPA 6.2%, NNPA 0.7%, PCR 90.1% |
Related Entities
Impact & Significance
- •Credit Expansion: Licensing large credit societies will improve credit delivery to micro-businesses, retail customers, and unorganized sectors in urban settings.
- •Institutional Resilience: Setting a high capital floor (₹300 crore) ensures that only entities with deep pockets and professional governance enter the banking space, reducing the risk of bank failures.
- •Level Playing Field: Equipping new UCBs with multi-state licenses and a wider footprint allows them to compete effectively against modern Small Finance Banks (SFBs) and NBFCs.
Challenges & Criticism
- •High Entry Barriers: The steep ₹300 crore minimum capital requirement and 10-year track record may lock out many well-performing, albeit smaller, credit societies from upgrading to banks.
- •Persistent Dual Regulation: Despite new entry norms, the fundamental issue of dual control (RBI and State RCS) remains, which can still lead to governance and administrative friction.
- •Concentration Risk: Currently, just 7% of UCBs hold 62.5% of the sector's deposits. Favoring only large societies for new licences might further exacerbate the divide between mega-UCBs and smaller cooperatives.
Future Outlook
- •Consultative Process: The RBI has invited public feedback on the proposal until February 13, 2026, ensuring stakeholder participation before finalized norms are issued.
- •Draft Licensing Guidelines: Following the public consultation period, the central bank will likely issue detailed draft licensing guidelines for further comments.
- •Enhanced Competition: Armed with strong capital bases, the newly licensed UCBs are expected to aggressively compete with SFBs and NBFCs, improving credit access in urban sectors.
UPSC Relevance
- • GS-3 (Economy): Banking sector reforms, financial inclusion, mobilization of resources, and cooperative banking.
- • Prelims Focus: Dual regulation of UCBs, differences between State and Multi-State Cooperative Societies Acts, and eligibility criteria (CAR, NNPA limits).
- • Mains Focus: Analyzing the systemic risks of the cooperative banking sector and the rationale behind the RBI's stringent new entry norms.
Sample Questions
Prelims
With reference to Urban Cooperative Banks (UCBs) in India, consider the following statements:
1. UCBs operate under a single regulatory framework governed exclusively by the Reserve Bank of India.
2. Under the new proposals, an applicant credit society must have a minimum capital of ₹300 crore to be eligible for a UCB licence.
3. UCBs can only be registered under the Multi-State Cooperative Societies Act.
Answer: Option 2
Explanation: Statement 1 is incorrect; UCBs operate under a dual regulatory framework (RBI and RCS). Statement 2 is correct; ₹300 crore is the proposed minimum capital requirement. Statement 3 is incorrect; they can be registered under either the State Cooperative Societies Act or the Multi-State Cooperative Societies Act.
Mains
Discuss the rationale behind the RBI's proposal to reopen the licensing window for Urban Co-operative Banks (UCBs) after a 22-year pause. How do the proposed eligibility filters address the historical vulnerabilities of the sector?
Introduction: Define Urban Co-operative Banks (UCBs) and highlight the context of the RBI's recent proposal to resume licensing after it was suspended in 2004.
Body:
• Rationale for Reopening: Need for greater financial inclusion in urban/semi-urban areas; fostering healthy competition with SFBs and NBFCs; capitalizing on the sector's improved overall health (Assets rising to ₹7.38 lakh crore, CAR at 18.0%).
• Historical Vulnerabilities: Dual regulation led to governance loopholes; the 2004 halt occurred because many newly licensed small banks quickly turned financially unsound and threatened depositor money.
• Addressing Vulnerabilities: The new framework mandates high entry barriers (₹300 crore minimum capital, 10-year track record) and strict financial health metrics (CAR > 12%, NNPA < 3%), ensuring only resilient credit societies become banks.
Conclusion: Conclude that by enforcing stringent eligibility filters and favoring multi-state societies, the RBI aims to balance credit expansion with systemic stability, ensuring UCBs fulfill their developmental mandate safely.